Menu
During the 2020-2022 period, I helped many first homebuyers achieve their dream of getting on the property ladder. I love my job, and it makes me super happy to see Kiwis get out from under a landlord and into their own home. First home buyers are my favourite – I love to educate them and give them the benefit of my many years lending and property investment experience.
Sadly, however, I had some clients over that period that struggled to make the leap into home ownership. Not because they didn’t have a bank approval – but because they procrastinated……
And the end result was that they went backwards financially.
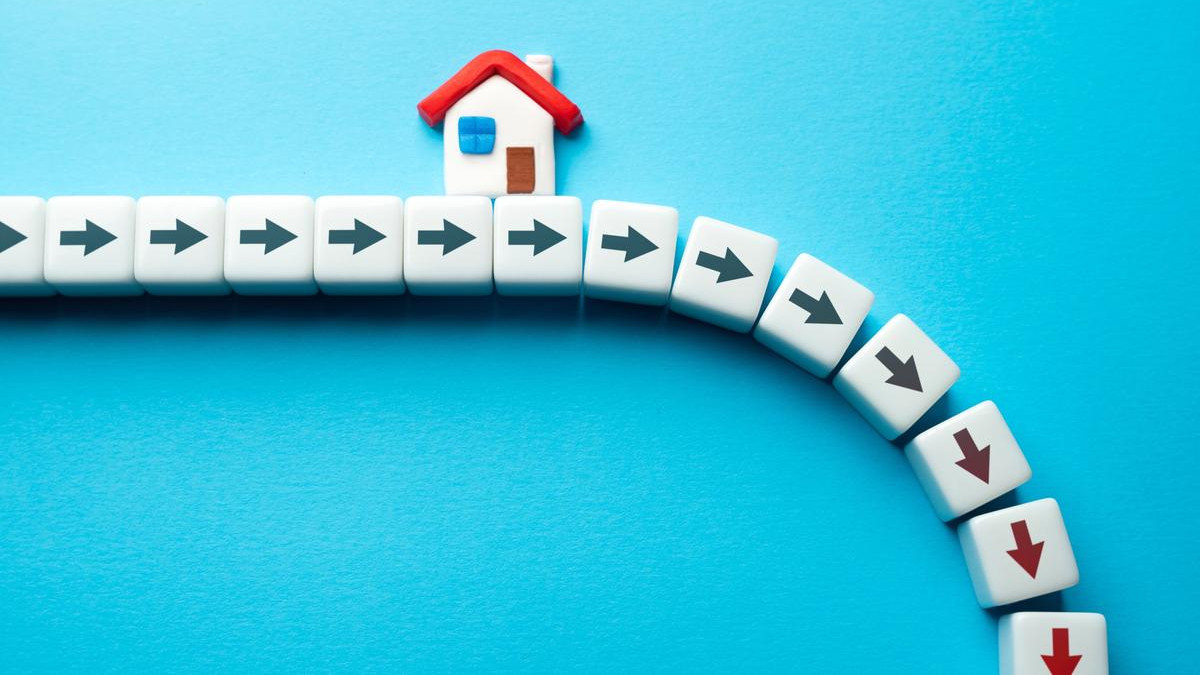
One such couple who lost focus on their goal, lost 20% buying power over that 2 year period, when they could’ve bought a really nice property, but didn’t. Interest rates went up, their loan affordability went down, and over the 2 years, the property price range they were shopping in reduced dramatically – until finally they needed parental help to get into a property, that they could’ve bought on their own if they’d acted 18 months earlier.
Often first home buyers are nervous. It is a big commitment ! They are worried about something going wrong, and not being able to meet their repayments. And that can happen – none can see the future. But we can protect ourselves as much as possible – your adviser will help you put structures in place to guard against the unexpected. Also, banks rigorously test an application’s debt servicing – the last thing a bank wants, is to see their loan fail, so they build fat into the calculations to minimise the risk.
Sometimes first home buyers are worried about paying too much – maybe if they wait a few months, the price will get lower. The truth ? If you are hopping on the property ladder for life – it doesn’t matter at all, what you pay. In 20 or 50 years – it just won’t matter. Even if you sell that property after 5 years and buy another. Doesn’t matter ! Buying and selling in the same market. The only time it is critical, is if you are speculating – planning to hold it for a short time only, then sell for profit. That’s something to keep away from unless you have a solid financial base, a lot of experience, and a big risk appetite.
Finally, first home buyers can be disappointed at the properties in their price range. They might be comparing with their parent’s home, or they are dreaming of a cottage with an oak tree and a swing……………Reality check – your first home does not have to be your dream home. It will probably not be your forever home. But you can make your mark on it, and it will get you on the ladder, and you can aim for something better down the track.
Just avoid houses that have not been maintained and will need expensive work done – like a re-roof – unless you have the savings put aside. Also steer clear of non-complying works – plenty of that in Northland.
If you are reading the commentary coming from various economists right now, indications are that we have probably hit the bottom of the property cycle, which means prices may start to rise from late this year. Don’t get caught napping like others did in the last cycle.
The best thing you can do at the start of your home ownership journey, is get a good adviser working with you. Someone to answer your questions, and keep you motivated and on track.


Now is a great time to review your loan structure. Chances are, due to the high interest rate environment we are in, you will likely be coming off lower rates than what’s available now and for some time.
Regardless of whether you have a loan due to be refixed soon or not, it’s always worth reviewing to ensure that it’s set up to meet your current and future plans and goals.
It may have been some time since you last did this but plans, circumstances, jobs, income and life stages change so it is vital you review to make sure the structure suits you and minimises interest paid to allow you to become debt free quicker.
Economic and interest rate forecasts also change so this is another reason to review to ensure the structure takes this, and your interest rate strategies and risk appetite into account.
The review may be as simple as a quick health check to confirm its suitable or may be more in depth and involve restructuring, breaking and refixing, tweaking the repayments, interest only periods, increased borrowing for home improvements etc.
Even minor changes such as increasing repayments can have a big impact on how quickly you can become debt free and reduce your interest costs, though this may be a challenge in the current high interest rate environment.
There are other ways to reduce interest costs such as utilising a revolving credit facility. All banks have this type of facility, ANZ call it a Flexible Home Loan, ASB an Orbit, BNZ Rapid Repay and Westpac Revolving Credit etc.
The key benefit of revolving credit is that it can save you interest by reducing your daily loan balance as much as possible. Revolving credit loans are transactional accounts, like an overdraft in many ways. You have your salary paid directly into this account thus reducing the balance, as interest is calculated daily you keep the balance as low as you can for as long as you can. You can also make lump sum payments into the account and withdraw again when needed.
Another way is an offset loan, these work by linking your savings account to a loan and you only pay interest on the difference between the two balances. For example, you have $50,000 in savings and an offset loan with a balance of $100,000, the two accounts are linked so you only pay interest on the difference – $50,000. These types of account are great for those who need to keep funds separate (e.g. provisioning for tax & GST) but want to use those savings to reduce interest costs. Only Westpac, Kiwibank and BNZ currently offer these facilities.
These are just some of the options available to assist in paying the mortgage off quicker, I am here to help so please get in touch to discuss as you could shave years off your mortgage and save money!